
Savings Goal Calculator
Work out what you need to put aside each month to hit a target, or how long a monthly amount will take to get you there. Enter the APY your account actually pays and this savings goal calculator returns a figure that lands on your goal to the cent, along with the weekly and daily equivalents and a year by year view of how the balance builds.
| Years | Monthly | You put in | Interest |
|---|
| Year | Added | Interest | Balance | Progress |
|---|
01 How much do you need to save each month?
The arithmetic is simple once you fix the four inputs: what you want, what you already have, how long you have, and what the money earns while it sits there. Here is what a $10,000 goal looks like from a standing start in an account paying 4.00% APY.
| Timeline | Monthly | Your deposits | Interest earned |
|---|---|---|---|
| 1 year | $818.43 | $9,821 | $179 |
| 2 years | $401.19 | $9,629 | $371 |
| 3 years | $262.18 | $9,439 | $561 |
| 5 years | $151.11 | $9,066 | $934 |
| 10 years | $68.17 | $8,180 | $1,820 |
Two things stand out. The monthly figure falls much faster than the timeline stretches, because you are dividing across more months and giving interest more time to work. And on a short goal the interest barely matters: over one year it covers $179 of a $10,000 target, under two percent of it.
That second point is worth holding onto, because a great deal of savings advice is written as though compound interest does the heavy lifting on every goal. On anything under about three years, you do.
02 How this savings goal calculator works
The calculator converts your APY into a monthly growth rate, then solves the standard future value of an annuity equation for the deposit that lands exactly on your target:
- Monthly rate
r = (1 + APY) ^ (1/12) - 1 - Grow what you already have:
FV = current x (1 + r) ^ months - Find the shortfall:
gap = goal - FV - Solve the deposit:
PMT = gap x r / ((1 + r) ^ months - 1)
Deposits are treated as arriving at the end of each month, which is the conservative assumption and matches how a standing transfer out of a monthly salary usually behaves. If you deposit at the start of the month instead, you will land slightly ahead of the figure shown.
Every payment the calculator returns was checked by forward simulation: apply that deposit month by month at that rate and the ending balance equals the goal to the cent. The two modes are also consistent with each other. Ask for the payment that clears a goal in sixty months, feed that payment back in, and the answer comes back sixty months. That was verified across 13,250 combinations of goal, starting balance, timeline and rate.
03 Why APY is the only rate you need
Plenty of savings calculators ask for an interest rate and then separately ask how often it compounds. If the rate you entered is an APY, that second question is not just unnecessary, it produces a wrong answer.
APY, the annual percentage yield, is defined as what you actually earn over a year after compounding has been accounted for. It is the number banks are required to advertise precisely so that accounts with different compounding schedules can be compared on one figure. If an account pays 4.00% APY, then $10,000 left alone becomes $10,400 after a year, whether the bank compounds daily, monthly or quarterly. The compounding is already inside the number.
So asking for it again and compounding a second time inflates the growth. On the previous version of this page, entering 4.5% APY and choosing monthly compounding applied an effective 4.594%, and choosing daily applied 4.6025%. Changing only that dropdown moved the required monthly deposit on a $10,000 five year goal from $148.63 to $152.33, on inputs that were otherwise identical. That dropdown has been removed.
If your bank quotes you a nominal rate rather than an APY, convert it once
and enter the result: APY = (1 + nominal/n) ^ n - 1, where n is
the number of compounding periods per year. Most US institutions advertise
APY directly, so in practice you can read it off your statement.
04 What compound interest is actually worth here
Compound interest is real and it is worth having, but its contribution depends almost entirely on how long the money sits. Saving $500 a month into an account at 4.00% APY:
| Period | You deposit | Interest | Balance | Interest share |
|---|---|---|---|---|
| 5 years | $30,000 | $3,090 | $33,090 | 9.3% |
| 10 years | $60,000 | $13,348 | $73,348 | 18.2% |
| 20 years | $120,000 | $61,921 | $181,921 | 34.0% |
At five years interest is under a tenth of the pot. At twenty it is a third. The curve is the whole story of compounding, and it is why the same advice can be excellent for a retirement horizon and close to irrelevant for a holiday you are taking next summer.
The honest size of the rate-chasing win
Moving from a typical high street savings account to a competitive one is worth doing, and it is worth doing for the right reasons. On a $10,000 goal, switching from the 0.38% national average to a 4.00% account changes the required monthly deposit like this:
| Timeline | At 0.38% | At 4.00% | Monthly saving | Total saving |
|---|---|---|---|---|
| 2 years | $415.15 | $401.19 | $13.96 | $335 |
| 5 years | $165.12 | $151.11 | $14.01 | $841 |
| 10 years | $81.78 | $68.17 | $13.61 | $1,633 |
About fourteen dollars a month, fairly consistently. That is a free fourteen dollars for one afternoon of paperwork, and over ten years it compounds into $1,633. But it is fourteen dollars, not hundreds, and it is worth saying so plainly. The previous version of this page claimed the switch "could save you hundreds in required monthly contributions". Hundreds is the lifetime total, not the monthly figure.
05 Where to keep the money
For a goal you intend to actually spend, the account matters less than the habit, but the differences are not nothing. As of 19 August 2026, NerdWallet lists top high yield savings rates at "up to a 4.21% annual percentage yield" against a "0.38% National avg."
| Where | Typical APY | Suits |
|---|---|---|
| High yield savings account | around 4% | Almost any goal you will spend within five years. Instant access, FDIC insured. |
| Certificate of deposit | varies by term | A hard deadline you will not move. Locks the rate, penalises early withdrawal. |
| Money market account | near HYSA rates | An emergency fund you may need to reach with a card or cheque. |
| Ordinary bank savings | 0.38% average | Nothing, if you have a goal. This is where most goal money quietly sits. |
Rates move with Federal Reserve policy and the ordering above can change, so check current rates rather than trusting a table on any page including this one. FDIC insurance covers up to $250,000 per depositor per insured bank per ownership category.
For goals more than ten years out, the calculation on this page stops being the right tool. Money that will not be touched for a decade or more is usually better served by a tax advantaged investment account than by a savings account, and the returns are neither fixed nor guaranteed, which is a different kind of maths entirely.
06 Inflation, and the part most savings calculators get wrong
If your goal is a number you picked because of what it buys today, inflation will move the goalposts before you arrive. A $50,000 deposit on a house is only a $50,000 deposit if house prices and everything else stand still.
There are two ways to handle this and they are not equivalent. The common approach is to shrink the interest rate to a real rate and leave the goal alone. That is arithmetically defensible, but it quietly assumes your monthly contribution rises with inflation every year, because a constant real contribution is a rising nominal one. The single figure it displays is therefore not the amount you can set up as a standing transfer and forget.
This calculator does it the other way round. Tick the inflation box and it raises your target to what it will cost in future dollars, then solves with your ordinary nominal APY. The figure you get is a constant monthly amount you really can automate, and it genuinely buys, on the target date, what your original number buys now.
| Goal in today's money | Timeline | Future cost at 3.4% | Monthly, unadjusted | Monthly, adjusted |
|---|---|---|---|---|
| $50,000 | 5 years | $59,098 | $755.53 | $893.00 |
| $50,000 | 10 years | $69,851 | $340.84 | $476.16 |
The inflation rate is an input rather than a fixed assumption, because any single figure is a guess and you should be able to see how much your answer depends on it. The default is 3.4%, the twelve month CPI change to July 2026. Annual averages over the last five years were 4.7%, 8.0%, 4.1%, 2.9% and 2.6%, an average of 4.46%, which shows how much the choice matters. The previous version of this page used 2.9% and described it as the five year average. It is the 2024 annual figure.
07 Habits that move the number
Move the money before you have a chance to allocate it elsewhere. The FDIC's own guidance puts it plainly: "Automatic transfers into savings on a set schedule can help you save money before you spend it." No comparative statistic is needed to see why this works.
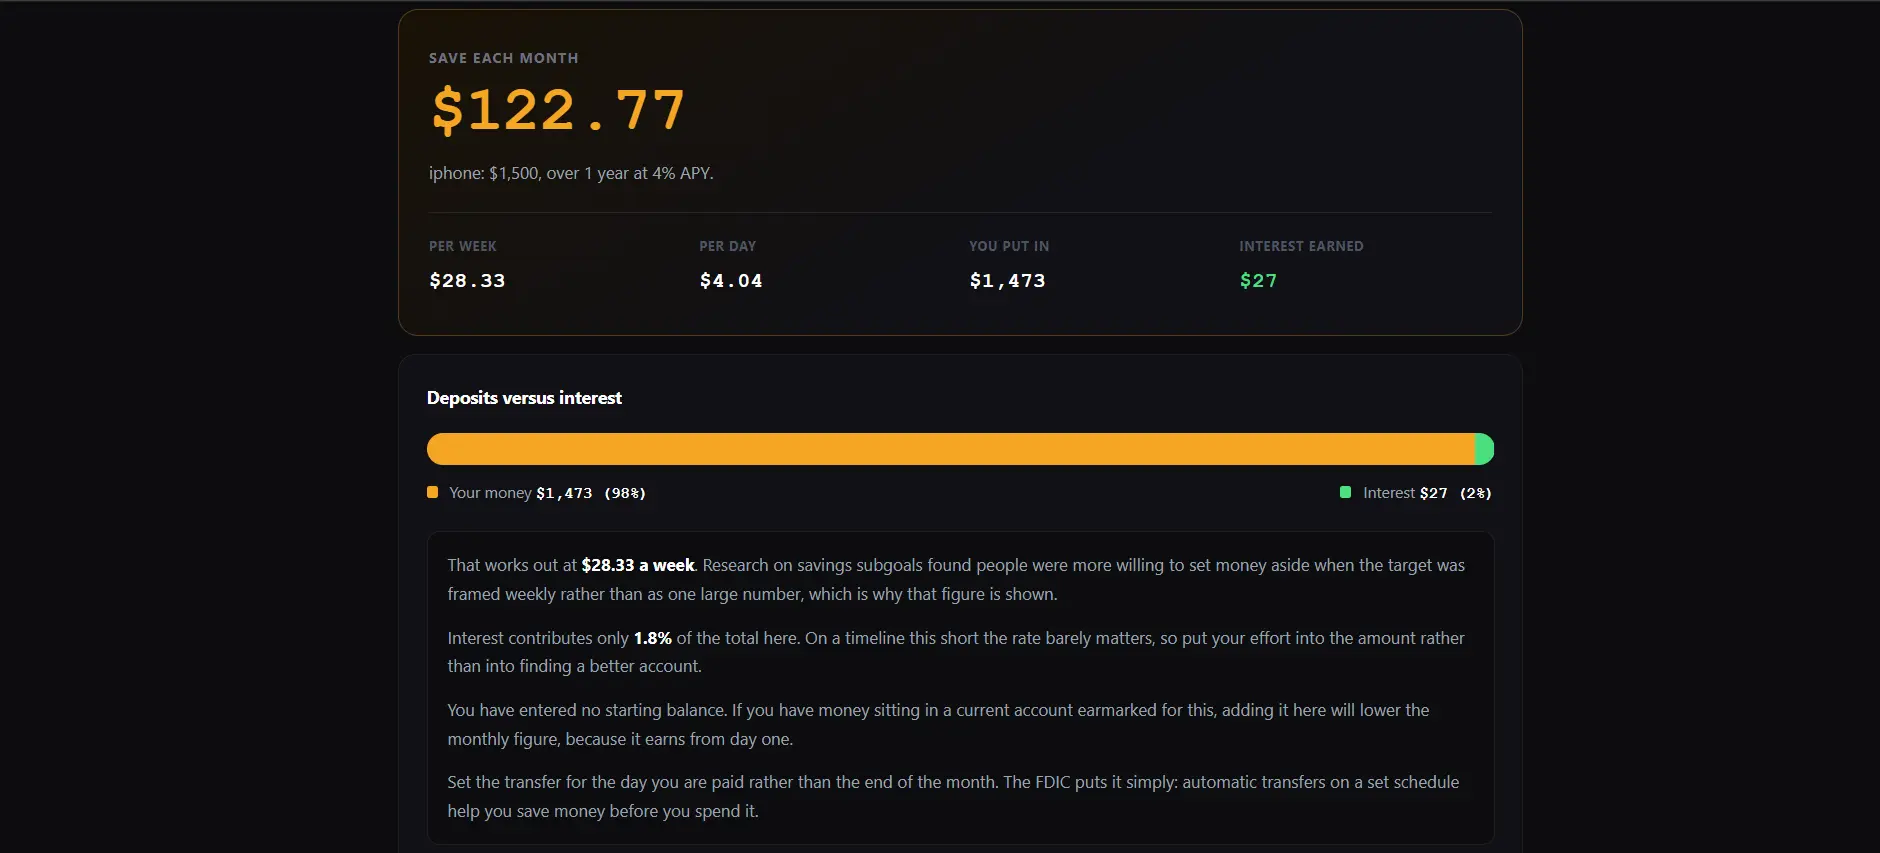
Colby and Chapman, in Judgment and Decision Making in 2013, found that "judgments were higher if the savings goal was presented as composed of weekly subgoals". People were more willing to forgo spending when the target was framed weekly. The calculator shows the weekly figure for this reason.
A dedicated account earns a better rate and puts a small amount of friction between you and the money. The friction is doing as much work as the rate.
A tax refund or bonus deposited as a lump sum cuts the monthly requirement permanently. On a $20,000 goal at 4.00%, a single $2,000 deposit reduces the monthly amount by $86.79 over two years, $58.98 over three, or $36.77 over five.
A raise, a rate cut, a missed month. The plan is only useful if it reflects where you actually are. Re-running this takes thirty seconds.
If you are saving for something enjoyable while carrying no buffer, the first unexpected bill will empty the goal account. Three to six months of essential costs, then the fun target.
08 Savings goal FAQ
From a standing start in an account paying 4.00% APY: $818.43 a month gets you there in a year, $401.19 in two years, $262.18 in three, $151.11 in five, and $68.17 in ten. Any amount you already have saved reduces all of these, because it earns interest for the whole period. Enter your own numbers above for an exact figure.
From zero at 4.00% APY: $200 a month takes 87 months, which is 7 years 3 months. $500 a month takes 38 months, or 3 years 2 months. $1,000 a month takes 20 months. Switch to the second tab above and enter your own monthly amount to see your timeline, including any balance you already hold.
The APY your account actually pays, which your bank is required to advertise and which appears on your statement. In August 2026 competitive high yield savings accounts pay around 4%, with NerdWallet listing top rates up to 4.21% against a national average of 0.38%. If your goal is several years out, consider entering something slightly below today's best rate, since rates move with Federal Reserve policy and you may not hold the same account throughout.
Because APY already includes it. Annual percentage yield is defined as what you earn across a year after compounding, which is exactly why banks quote it: it lets you compare accounts with different compounding schedules on a single number. An account paying 4.00% APY turns $10,000 into $10,400 in a year regardless of whether it compounds daily or quarterly. Asking for the frequency again and applying it a second time overstates growth, which is what the earlier version of this page did.
It depends almost entirely on the timeline. Saving $500 a month at 4.00% APY, interest accounts for 9.3% of your balance after five years, 18.2% after ten and 34.0% after twenty. On a one year goal the effect is small: reaching $10,000 in twelve months, interest contributes $179 of it. Compounding rewards time far more than it rewards rate, which is why the same advice is transformative for retirement and close to irrelevant for next year's holiday.
Tick the inflation box and the calculator raises your target to what it will cost in future dollars, then solves with your ordinary APY. That gives a constant monthly amount you can genuinely automate. Saving for something that costs $50,000 today, over five years at 3.4% inflation, the real target is $59,098 and the monthly figure rises from $755.53 to $893.00. The rate is editable because any single assumption is a guess: US annual CPI averaged 4.7%, 8.0%, 4.1%, 2.9% and 2.6% across 2021 to 2025.
Yes, though the size of the win is often overstated. On a $10,000 goal, moving from the 0.38% national average to a 4.00% account reduces the required monthly deposit by about $14, fairly consistently across timelines. Over two years that is $335 in total, over five $841, over ten $1,633. Worth an afternoon of paperwork, but it is $14 a month rather than a transformation, and the habit of transferring on pay day will move your number far more.
The most commonly cited guideline is the 50/30/20 rule, from Elizabeth Warren and Amelia Warren Tyagi's 2005 book "All Your Worth", which allocates 20% of take home pay to savings and debt repayment combined. Treat it as a starting reference rather than a rule: it predates current housing costs, and the right figure depends on your rent, your debts and how urgent your goal is. This calculator answers a narrower and more useful question, which is what one specific goal requires.
No. Every calculation runs in your browser. No amount, rate or goal name is transmitted to a server, stored, or shared. Nothing persists between visits, so closing the tab discards everything. There is no sign up and no account.
09 Limits, sources and disclaimer
What this does not model
Tax on interest, which in a taxable account reduces your effective return. Account fees and minimum balance requirements. Rate changes partway through, which are likely over any multi year period since savings rates are variable. Missed or irregular contributions. Withdrawals. Employer matching. It assumes one fixed deposit at the end of every month at one unchanging rate, which is a planning model rather than a forecast.
Sources
The annuity method matches the approach used by the SEC's Investor.gov savings goal calculator. Savings rates and the national average from NerdWallet's high yield savings roundup, current as of 19 August 2026. Inflation figures from the BLS Consumer Price Index. Automatic transfer guidance quoted from the FDIC consumer resource on saving. Subgoal research from Colby and Chapman, Judgment and Decision Making, 2013. Every figure quoted here was read on the linked page, in line with the Editorial Policy.
An earlier version of this page attributed a claim that people who automate savings "save 2 to 3 times more" to FDIC research, cited the Journal of Consumer Research for a finding on intermediate milestones, described 2.9% as the five year average CPI, and quoted HYSA rates of 4.0% to 5.0%. No such FDIC statistic exists, the subgoal study is Colby and Chapman in Judgment and Decision Making and concerns weekly rather than annual subgoals, 2.9% is the 2024 annual figure rather than a five year average, and top savings rates in August 2026 are around 4.2%. Several worked examples were also recomputed: the $10,000 three and five year figures, the $500 and $400 monthly growth examples, and all three $20,000 timelines.
Not financial advice
Calcxi is an independent calculator site. It is not a bank, adviser or broker, and it is not affiliated with Investor.gov, the SEC, the FDIC or any financial institution. This page is educational. Speak to a qualified adviser before making significant savings or investment decisions.
10 Related calculators
Written & verified by
B.Tech Computer Science · 8 years in web development & SEO · Bhilwara, India
About ·
LinkedIn ·
Report an error