
Credit Card Payoff Calculator
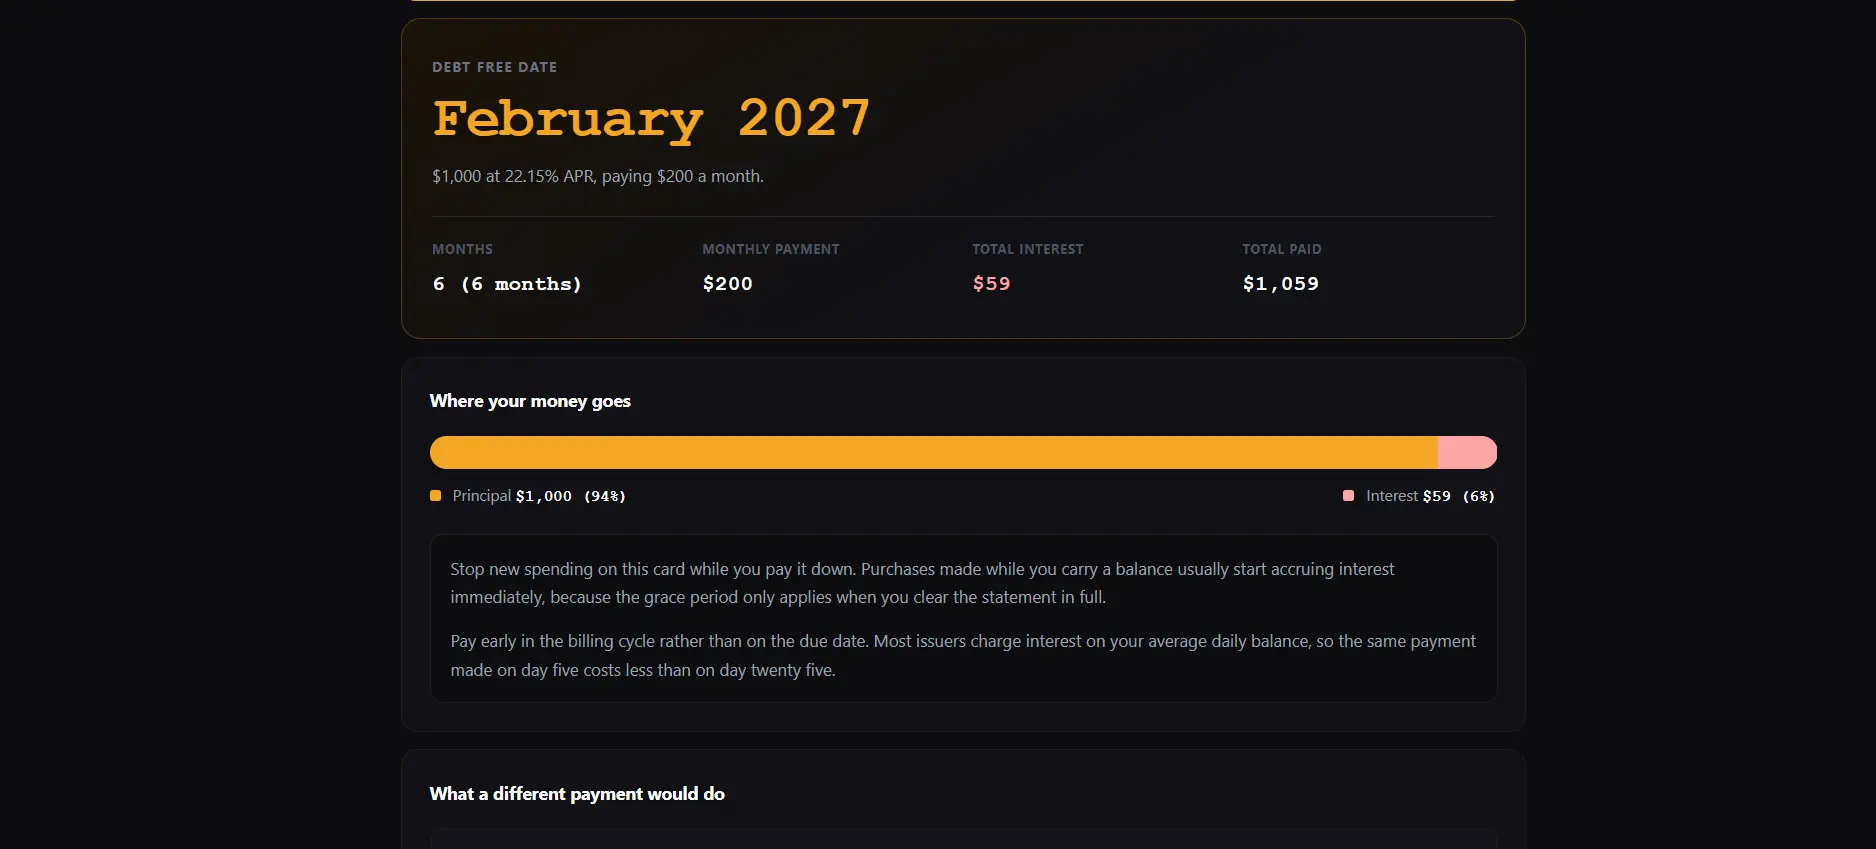
Find your debt free date and the total interest it will cost to get there. This credit card payoff calculator runs the same month by month amortisation your issuer does, so you can see exactly what a fixed payment, a target date, or minimum payments alone would mean. Add up to five cards to compare the avalanche and snowball methods against your own numbers.
| Monthly payment | Months | Total interest | vs your plan |
|---|
01 How long will it take to pay off your credit card?
It depends on three numbers and nothing else: your balance, your APR, and what you actually pay each month. The third one is the only one you control in the short term, and it dominates the other two.
Take a $5,000 balance at 22.15%, the current Federal Reserve average for accounts carrying a balance. Here is what different monthly payments produce. These come from the same engine that powers the calculator above.
| Monthly payment | Time to clear | Interest paid | Total paid |
|---|---|---|---|
| $100 | 11 years 9 months | $9,012 | $14,012 |
| $150 | 4 years 5 months | $2,834 | $7,834 |
| $200 | 2 years 10 months | $1,768 | $6,768 |
| $300 | 1 year 9 months | $1,031 | $6,031 |
| $500 | 1 year | $579 | $5,579 |
Look at the first two rows. Going from $100 to $150 a month, an extra $50, cuts the payoff from 11 years 9 months to 4 years 5 months and saves $6,178 in interest. That is 88 months and more than the original balance, bought with $50 a month. The relationship is not linear, and it is steepest exactly where most people are paying.
02 How this credit card payoff calculator works
Each month the calculator repeats four steps, which is the same sequence your issuer follows:
- Work out this month's interest: current balance multiplied by APR divided by twelve.
- Add that interest to the balance.
- Subtract your payment from the new balance.
- Carry the remainder into next month and repeat until it reaches zero.
Because interest is charged before your payment lands, the early months of any payoff go overwhelmingly to interest. On a $5,000 balance at 22.15%, the first month's interest is $92.29. If you pay $100 that month, $7.71 comes off what you actually owe.
The calculator is a planning model, not a statement replica. Real issuers use your average daily balance rather than the month end balance, apply payments to higher rate portions first under the Credit CARD Act of 2009, and may add fees this model does not include. Expect your real figures to land close to these but not identical.
03 Why minimum payments keep you in debt
Almost every article on this subject says minimum payments will keep you in debt for decades, and almost none of them say which minimum. That omission matters more than the headline, because the formula your issuer uses changes the answer by decades.
Here is the same $5,000 balance at 22.15%, paid at the minimum under each of the three formulas issuers actually use, with a $25 floor:
| Minimum payment formula | Time to clear | Interest paid |
|---|---|---|
| 3% of the balance | 16 years 8 months | $6,830 |
| Interest plus 1% of principal | 19 years 3 months | $8,159 |
| 2% of the balance | 72 years | $38,451 |
That last row is not a typo. At 22.15% APR, monthly interest is 1.85% of the balance. If your minimum is 2% of the balance, only 0.15% of the balance comes off the principal each month. The debt shrinks so slowly that it takes over seventy years and costs more than seven times the original balance.
This is why the minimum payment formula printed on the back of your statement is worth two minutes of your attention. Switch the calculator above to minimum payments only and enter your own formula to see your number.
The Credit CARD Act of 2009 requires every statement to disclose how long minimum only payments would take and what they would cost. Most people never read that box. The point of this tool is to make that number harder to ignore.
04 Avalanche vs snowball: which pays off credit card debt faster?
Both methods pay the minimum on every card and put every spare dollar into one target card. They differ only in which card gets targeted.
Avalanche targets the highest APR first. This produces the lowest total interest, because it removes the most expensive debt soonest. Building this page, the two strategies were run against 32,500 generated combinations of balances, rates and extra payments, and avalanche never came out more expensive than snowball in any of them.
Snowball targets the smallest balance first. It usually costs somewhat more in interest, but it clears whole accounts faster, and the argument for it has always been behavioural rather than mathematical.
That argument has some evidence behind it. Gal and McShane, writing in the Journal of Marketing Research in 2012, analysed roughly 6,000 clients of a debt settlement firm and found, in Kellogg Insight's summary, that "the number of accounts closed better predicted successfully completing the program than the dollar amount an individual had paid off." Worth noting that these were debt settlement clients rather than ordinary cardholders, so it is suggestive rather than conclusive for your situation.
The practical answer: run both in the calculator above with your own cards. If avalanche saves you a few hundred dollars, take whichever you will actually finish. If it saves you a few thousand, that is worth some discomfort.
The rollover effect, which both methods share
When a card is cleared, its minimum payment does not disappear from your budget unless you let it. Rolling that freed minimum into the next target card accelerates every subsequent payoff without costing you another dollar a month. The calculator models this, which is why the later cards in the payoff order clear much faster than the earlier ones.
05 What a lower APR is actually worth
The cheapest move available to most cardholders is a phone call. LendingTree surveyed cardholders between 14 and 16 May 2025 and reported that "83% of those who asked for a lower interest rate on a credit card in the past year got one", with "the average reduction was 6.7 points".
A 6.7 point cut is not a rounding difference. On a $5,000 balance paid at $200 a month, dropping from 22.15% to 15.45% takes the interest from $1,768 to $1,073, a saving of $695, and clears the balance three months sooner. On larger balances the saving scales with it.
The call costs nothing beyond the time. Ask for the retention or account review department, mention how long you have held the account, and if you have a competing offer in hand, say so. The worst outcome is that nothing changes.
One caveat worth stating plainly: that 83% figure describes people who asked, not everyone. Cardholders who ask are likely to skew towards those in good standing with reasonable credit, so treat it as encouraging rather than as your personal odds.
06 Is a balance transfer worth the fee?
A 0% balance transfer card charges a fee, typically 3% to 5% of the amount moved, in exchange for a promotional window with no interest. The trade only works if you clear the balance inside that window.
Here is the actual arithmetic on a $5,000 balance at 22.15%, comparing the interest you would avoid against the fee you would pay:
| Promo window | Payment needed | Interest avoided | Net of 3% fee | Net of 5% fee |
|---|---|---|---|---|
| 12 months | $468 | $620 | $470 | $370 |
| 15 months | $385 | $770 | $620 | $520 |
| 18 months | $329 | $922 | $772 | $672 |
| 21 months | $289 | $1,077 | $927 | $827 |
So a balance transfer on $5,000 is worth somewhere between $370 and $927, depending on the window and the fee. Real, but smaller than the way these cards are usually marketed. Note the payment column: to capture the full benefit of a 12 month window you have to pay $468 a month. If you cannot, the remaining balance reverts to a standard APR when the promotion ends, and that rate is often higher than what you left.
07 Current credit card rates and debt levels
Knowing where your own APR sits against the average tells you whether asking for a reduction is likely to be worth the call.
| Measure | Latest | Source and period |
|---|---|---|
| Average APR, accounts assessed interest | 22.15% | Federal Reserve G.19, Q2 2026 |
| Average APR, all accounts | 20.94% | Federal Reserve G.19, Q2 2026 |
| Total US credit card balances | $1.26 trillion | NY Fed Household Debt and Credit, Q2 2026 |
| Card debt flowing into serious delinquency | 6.97% | NY Fed Household Debt and Credit, Q2 2026 |
The two APR figures differ because the first covers only accounts that carry a balance and therefore pay interest, while the second averages across all accounts including those paid in full each month. If you are carrying a balance, 22.15% is your comparison point.
These figures move with Federal Reserve policy and are updated quarterly. The G.19 release date for the current figures was 7 August 2026. Check the current G.19 release if you are reading this some months later.
08 Credit card payoff FAQ
It depends on your balance, APR and monthly payment. A $5,000 balance at 22.15%, the Federal Reserve's Q2 2026 average for accounts carrying a balance, takes 34 months at $200 a month and costs $1,768 in interest. The same balance at $100 a month takes 11 years 9 months and costs $9,012. Enter your own numbers in the calculator above for your exact date.
Avalanche puts every spare dollar into the card with the highest APR, which always produces the lowest total interest. Snowball puts it into the smallest balance, which clears whole accounts sooner and usually costs somewhat more. Both pay minimums on everything else, and both roll a cleared card's minimum into the next target. Run both on your own cards in the Multiple cards tab to see your actual difference in dollars and months.
That depends on your issuer's minimum payment formula, which changes the answer by decades. On $5,000 at 22.15% with a $25 floor: a 3% of balance minimum clears in 16 years 8 months costing $6,830; interest plus 1% of principal takes 19 years 3 months and $8,159; a flat 2% of balance minimum takes over 70 years and costs $38,451, because monthly interest at that APR is 1.85% of the balance and only 0.15% comes off the principal. Check which formula your statement uses, then use the minimum payments only mode above.
Any amount helps, and the effect is largest when your current payment is smallest. On $5,000 at 22.15%, going from $100 to $150 a month cuts the payoff from 11 years 9 months to 4 years 5 months and saves $6,178 in interest. On $20,000 at the same rate, going from $500 to $600 saves 21 months and $5,314. The calculator shows a payment ladder with your own figures so you can see where the curve is steepest for you.
Often, yes. LendingTree surveyed cardholders in May 2025 and found that 83% of those who asked for a lower rate in the past year received one, with an average reduction of 6.7 percentage points. That figure describes people who asked rather than everyone, so it likely skews towards accounts in good standing. The call costs nothing to attempt. Ask for the retention or account review department and mention how long you have held the card.
On a $5,000 balance at 22.15%, a transfer nets you between $370 and $927 depending on the promotional window and whether the fee is 3% or 5%. It is worth doing if you can clear the balance inside the window, which means paying $468 a month for a 12 month promotion or $289 for a 21 month one. If the balance survives the promotion it reverts to a standard APR, often higher than the rate you left.
The Federal Reserve G.19 for Q2 2026 puts the average at 22.15% for accounts assessed interest and 20.94% across all accounts. If your rate is above 22.15% you are paying more than the typical balance carrier, which makes a call to your issuer worth the time. Rates below the average generally reflect stronger credit profiles or older accounts.
Clearing a balance at 22.15% is equivalent to a guaranteed, tax free 22.15% return, which is well above what a diversified portfolio has historically returned over the long run. The usual exception is an employer retirement match, which is an immediate return you cannot get back later. Beyond that, high rate card debt is almost always the better use of a spare dollar. This is general information rather than advice for your circumstances.
No. Every calculation runs in your browser. No balance, rate or payment amount is transmitted to a server, stored, or shared. Nothing is saved between visits, so closing the tab discards everything you entered. There is no sign up and no account.
09 Limits, sources and disclaimer
What this calculator does not model
Annual fees, late fees, over limit fees, cash advance rates, penalty APRs triggered by a missed payment, promotional rates expiring mid payoff, new purchases added to the balance, and the difference between average daily balance and month end balance billing. Any of these will move your real figures away from these. The results are a planning bracket, not a statement.
Sources
APR figures from the Federal Reserve G.19 Consumer Credit release of 7 August 2026, Q2 2026 data. Balance and delinquency figures from the New York Fed Household Debt and Credit report for Q2 2026. APR reduction survey from LendingTree's study of lower APR requests, fielded May 2025. Repayment behaviour research from Kellogg Insight's summary of Gal and McShane (2012). Every figure quoted on this page was read on the linked page, in line with the Editorial Policy.
An earlier version of this page used 21.52% labelled Q1 2026, gave total card debt as $1.25 trillion, cited a "2026 LendingTree survey" reporting 84% success and a 6.3 point average reduction plus a claim that only 23% of cardholders ever ask, listed a 23.79% new offer APR and a 2.94% delinquency rate, and stated that a balance transfer eliminates "well over $1,000" in interest on $5,000. The current figures are 22.15% and $1.26 trillion, LendingTree's actual study reports 83% and 6.7 points from May 2025 with no figure for how many ask, the new offer and delinquency rows could not be found on the sources credited and have been removed, and the balance transfer benefit is $620 to $1,077 before the fee.
Not financial advice
Calcxi is an independent calculator site. It is not a bank, lender, credit counselling agency or financial adviser, and it is not affiliated with any card issuer. This page is educational. For advice on your own situation, speak to a qualified adviser or a nonprofit credit counselling agency. In the United States the Consumer Financial Protection Bureau publishes free guidance on credit card debt.
10 Related calculators
Written & verified by
B.Tech Computer Science · 8 years in web development & SEO · Bhilwara, India
About ·
LinkedIn ·
Report an error